The employee filling in for Rita Crundwell asked for all of Dixon's bank statements. One of them showed an account the mayor did not know existed.
Case brief
Dixon, Illinois · 1990–2012
- Recorded outcome
- Pleaded guilty in 2012; sentenced in 2013; listed as a recipient of a federal commutation on December 12, 2024.
Key moments
People and case photographs
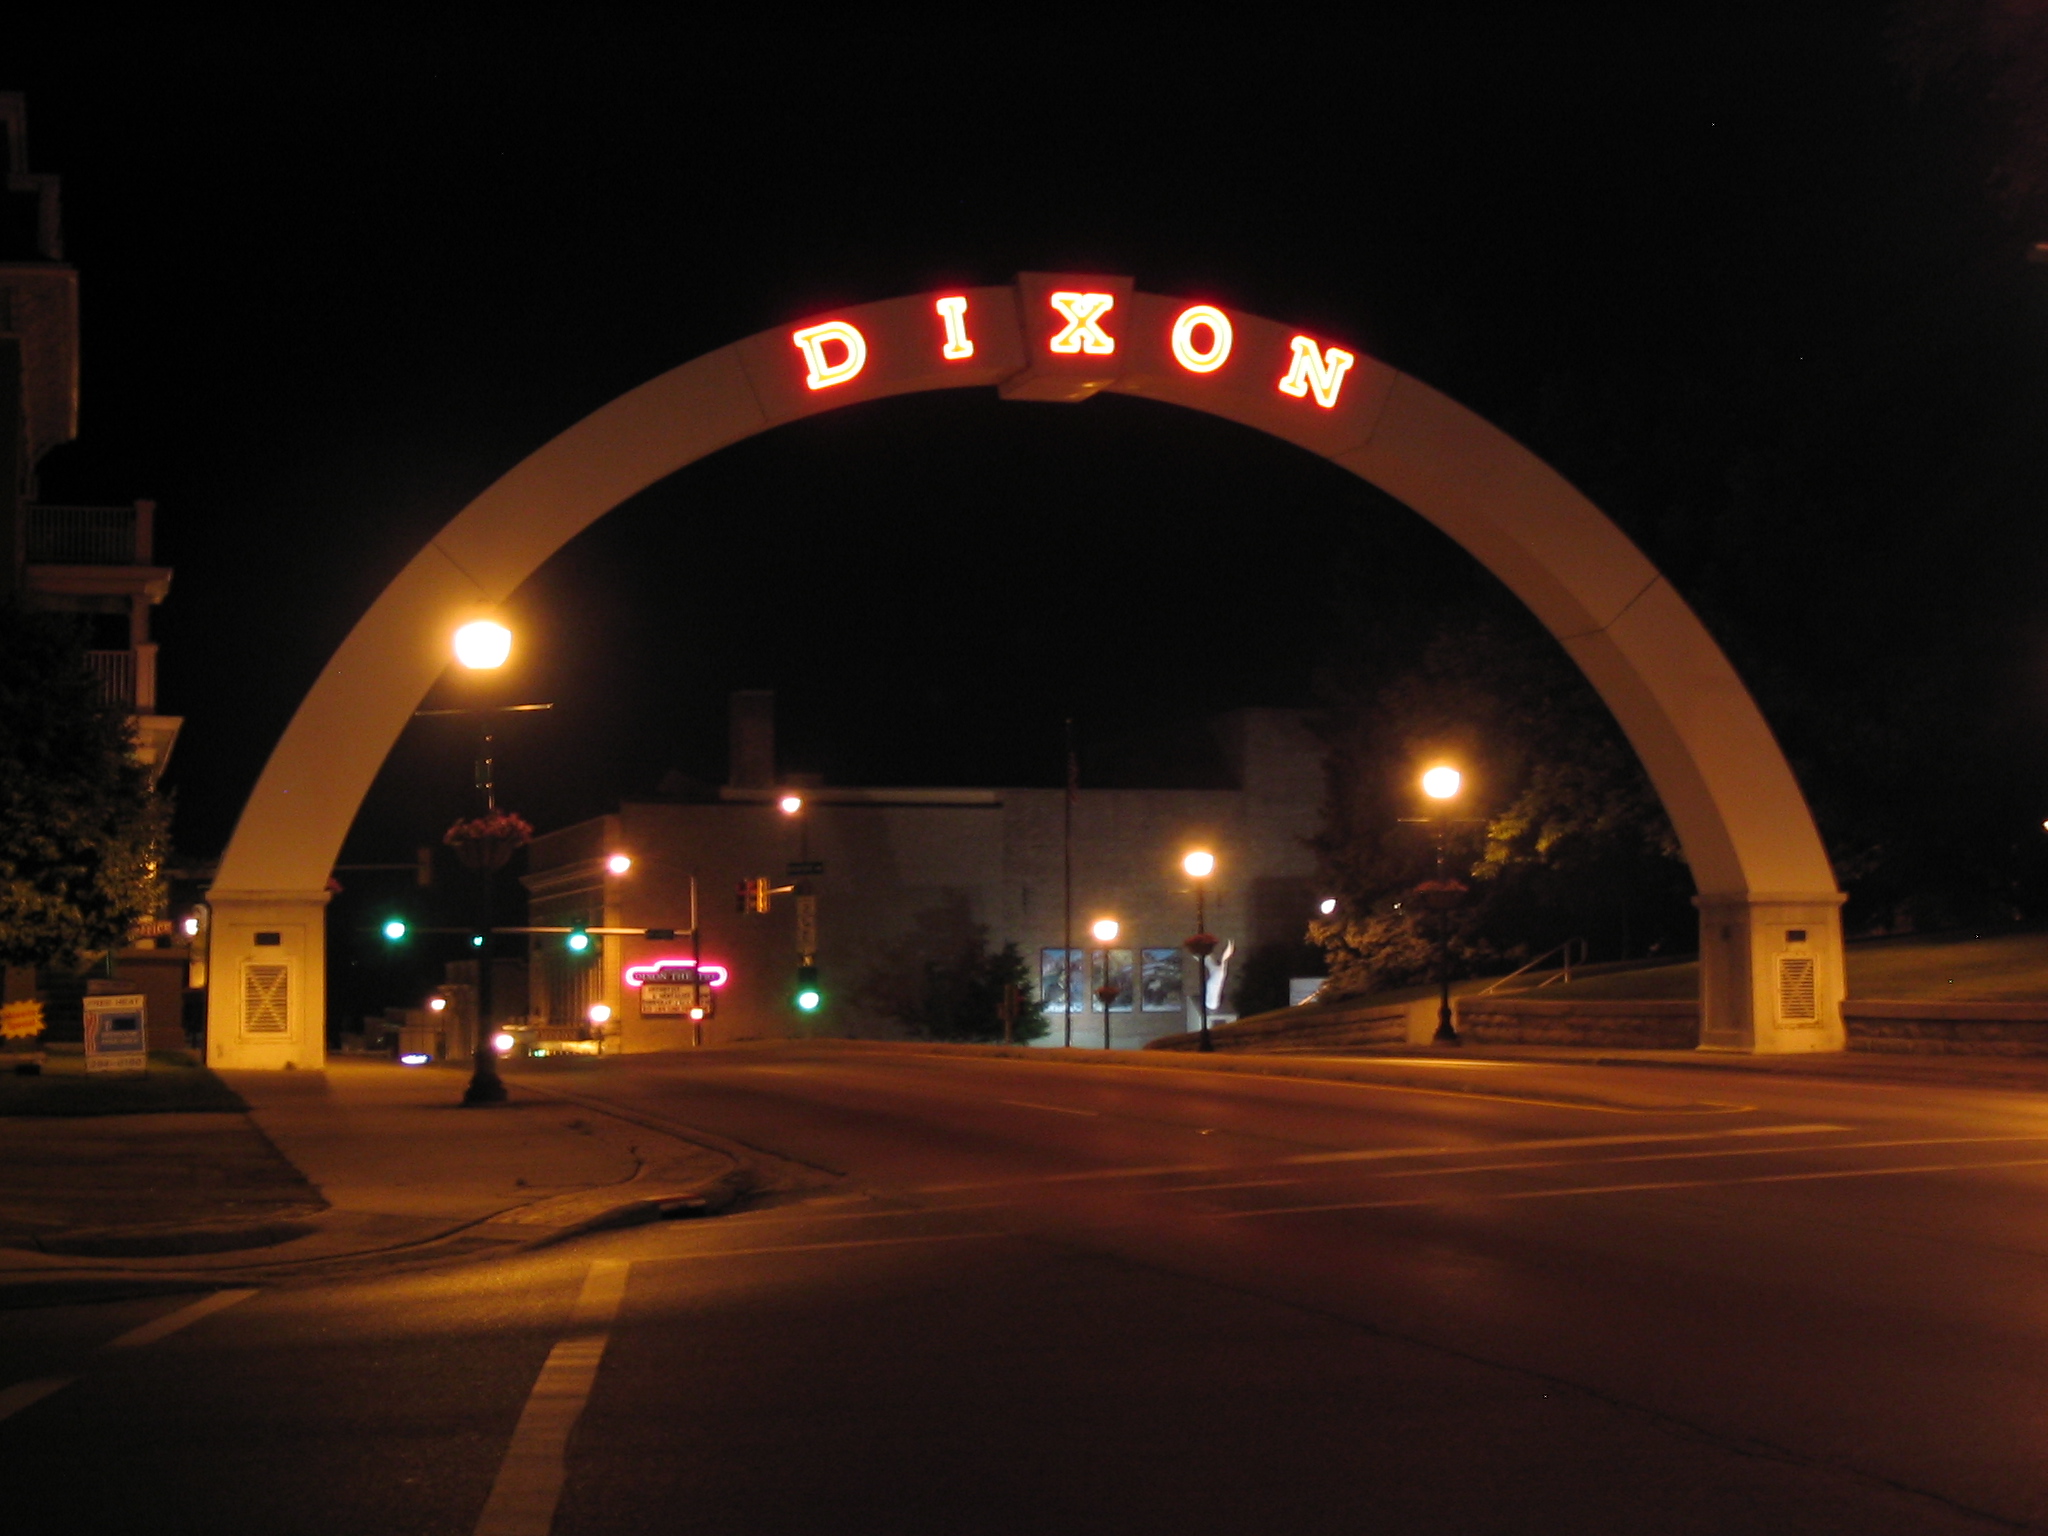
Galena Avenue in Dixon, Illinois The city’s memorial arch in 2007, during the years Rita Crundwell served as comptroller and diverted municipal funds.
Location photograph · Framerotblues via Wikimedia Commons · Public domain dedication- Rita Crundwell
Pleaded guilty to federal wire fraud
Photo at source · WGLT · captioned file photograph
That request, made while the Illinois city's longtime comptroller was on an extended absence in 2011, exposed the route through which she had diverted public money for two decades. By the time the federal case reached sentencing, the theft totaled approximately $53.7 million. [1]
A career inside the finances
Crundwell began working in Dixon's finance department in 1970, while she was still in high school. She became comptroller and treasurer in 1983.
The job placed her inside the processes that moved the city's money. She could arrange transfers, prepare documents and explain the state of the budget to officials who relied on the financial information she supplied.
On December 18, 1990, she opened a bank account in the city's name that she alone controlled. Its initials, RSCDA, stood for Reserve Sewer Capital Development Account. Despite the municipal-sounding label, the account was not a legitimate city reserve of the kind its name suggested.
Transfers into it began in January 1991. Prosecutors' sentencing account described more than $181,000 moved that year. The annual theft eventually reached $5.8 million in 2008. Across the scheme, the average exceeded $2.5 million a year. [1]
Those figures describe an accumulating loss, not a single spectacular withdrawal. The duration depended on keeping each year's transactions inside an apparently routine financial structure.
The budget story and the hidden spending
Crundwell took part in budget meetings with council members and department heads. According to the government's account of her admitted conduct, she blamed the city's financial difficulties on the economy and late payments from the state.
At the same time, she was directing public funds into her own expenses and horse operations. The city cut its budget while money that should have been available for public purposes financed a very different set of priorities.
The contrast was concrete. Crundwell owned RC Quarter Horses, with animals kept at her Dixon ranch, a Wisconsin ranch and trainers' facilities around the country. The property later seized or restrained included homes, farmland, a luxury motor home, vehicles, a boat and jewelry.
The assets made the theft visible after investigators uncovered it. Before then, the scheme depended less on hiding every sign of wealth than on hiding the financial connection between that wealth and the city treasury.
A sewer invoice and a quarter horse
One transaction described at sentencing showed the money's path.
On September 8, 2009, Crundwell moved checks for $150,000 and $200,000 from two city accounts into the Capital Development Fund. Later that day, she wrote a $350,000 check payable to the treasurer and deposited it into the secret RSCDA account.
A fictitious invoice supplied an explanation: the payment supposedly covered a sewer project completed by the State of Illinois.
Crundwell then moved $225,000 from the secret account into her horse business's account. That deposit covered a check for a quarter horse named Pizzazzy Lady. The government said the horse-purchase check would not have cleared without the infusion of city money. [1]
The transaction combined legitimate-looking account names and documents with an unauthorized destination. A reviewer shown the invoice might see a public project. Following the money revealed a private purchase.
Prosecutors counted 159 fabricated invoices purporting to come from the state. The false records were a repeated means of explaining transfers, not a one-time effort to disguise an unusual expense.
Who saw the mail
Control of the bank statements helped the scheme survive. Crundwell collected the city's mail, including statements for the secret account. When she was away, she arranged for mail to be picked up and separated so that those statements would not come to other employees' attention.
The routine broke during her extended absence in 2011. The employee handling her duties requested the city's bank statements and noticed the unfamiliar account. The records went to the mayor, who contacted law enforcement that fall. [1]
The discovery did not require guessing from Crundwell's lifestyle or assigning motives to coworkers. It began with a document that showed something inconsistent with the city's understood financial arrangements.
That matters when considering how the crime was uncovered. The decisive question was not simply whether Crundwell owned expensive things. It was whether the government money under her control was going where the city had authorized it to go.
The conviction and the assets
Crundwell was arrested on April 17, 2012. She pleaded guilty to wire fraud on November 14 of that year. On February 14, 2013, a federal judge sentenced her to 235 months in prison—19 years and seven months.
The court ordered restitution of $53,740,394 and entered a forfeiture judgment. Authorities also pursued the sale of assets, including approximately 400 horses and related property. [1]
Restitution orders and asset sales address different parts of the aftermath. An order establishes an obligation; a sale turns a particular asset into money. Neither alone proves that a victim has recovered the full amount taken. The 2013 announcement reported the recoveries then available, not a final accounting for every later collection or settlement.
For Dixon, the victim was also a municipal government serving residents. Public money spent privately was money unavailable for the public purposes for which it had been collected.
The practical problem of returning the money
Once assets were seized, investigators faced property that could not simply remain in an evidence locker. Hundreds of horses needed continuing care while authorities arranged their sale. The Marshals Service held a live auction in Dixon on September 23 and 24, 2012, selling horses and related equipment. Its contemporary account put that sale and other September auctions together at $7.2 million. This was an interim recovery figure, months before sentencing. [3]
By the February 2013 sentencing announcement, reported sales exceeded $12.38 million. The property sold included horses, vehicles, trailers, tack, a motor home, jewelry and personal belongings. Nearly $9.5 million in net proceeds was being held in escrow pending restitution proceedings; Illinois and Florida real-estate sales remained pending. The gross proceeds, net proceeds and amount actually distributed to Dixon were therefore not interchangeable totals. [1]
That distinction gives the horse operation a second place in the story. It had absorbed stolen public funds, but selling it did not reverse every dollar of spending. Expenses and the changing value of individual assets stood between seizure and recovery. The federal announcement documents a snapshot of that process, rather than a final balance sheet for the city. [1]
The harm beyond the account balance
The sentencing judge also considered damage that would not fit neatly into an auction ledger. He found disruption of government services and a loss of public confidence, and granted the government's request for a sentence above the advisory guideline range. The reasoning connected the private purchases with the public budget: residents had experienced constraints on city services while their comptroller was diverting the money. The restitution order recorded the financial obligation; the sentencing explanation addressed why the breach of public trust mattered as well. [1]
A later change to the sentence
Crundwell's story did not end with the 2013 prison term. The Justice Department's Office of the Pardon Attorney lists Rita A. Crundwell among the recipients of federal commutations dated December 12, 2024. [2]
A commutation changes a sentence. It is not an acquittal, a finding that the money was never stolen or a reversal of the guilty plea. An account that stops at the original prison term therefore misses an important later development; an account that calls the commutation exoneration gets the development wrong.
The underlying record remains unusually detailed about how an enormous theft became routine. Funds passed through municipal accounts. False invoices supplied a cover story. Bank statements were kept from view. When a substitute employee requested the full set of statements, the hidden account finally became a question someone else could ask.
Look closer · 3 visuals
Inside the evidence.
Open a visual to explore what it contributed to the case—and the limits of what it shows. These original illustrations explain the record; they are not photographs of the actual evidence.
The statements someone else requested
Original editorial illustration — not an actual evidence photograph or exhibit.
Read the evidence notes
The full bank statements exposed an account the mayor did not know existed.
Not real statements or account numbers. The illustration marks the discovery of the concealed account.
A sewer invoice and a horse
Original editorial illustration — not an actual evidence photograph or exhibit.
Read the evidence notes
The September 2009 records traced city funds through the concealed account to a quarter-horse purchase.
Generic horse, not Pizzazzy Lady. No authentic invoice or signature reproduced.
From assets to restitution
Original editorial illustration — not an actual evidence photograph or exhibit.
Read the evidence notes
Sales turned assets into money, but gross proceeds, net proceeds and restitution obligations were distinct.
Recovery context, not a claim that Dixon had been fully repaid.
★ Key evidence used in a conviction · ✓ Exclusion or reversal · ◇ Disputed evidence · ⊘ Excluded at retrial · ◆ Identity / investigative finding, not a conviction. A symbol does not mean one item proved the whole case.
Follow the locations
Put the story on the map.
Follow the dated entries, then select an event to find its regional setting. Shared-location pins open a group of events. Evidence symbols identify important findings and their limitations.
Open the map in its own window ↗Sources & further reading
- Former Dixon Comptroller Rita Crundwell Sentenced for $53.7 Million TheftPlea, 235-month sentence, scheme chronology, account discovery, fake invoices, city impact, assets and restitution order.
- Office of the Pardon Attorney: December 12, 2024 Commutation RecipientsRita A. Crundwell's inclusion in federal commutation list, not exoneration or a current restitution balance.
- U.S. Marshals Service: September 2012 Crundwell auctionAgency account of September 23–24 auction and contemporary combined auction proceeds.
Editorial review: 2026-09-30 · 1327 words